

The Bilt Palladium Card has a $495 annual fee (Rates & Fees), and it’s a Mastercard credit card serviced by Cardless. As I see it, this is the most lucrative card in the Bilt credit card portfolio — it offers a solid welcome bonus, an incredible return on spending, and is particularly worthwhile for anyone who makes housing payments (and eventually potentially those who don’t). After all, earning rewards for housing payments is one of the key value propositions of the Bilt ecosystem.
I’ve written a guide to Bilt credit cards, and in general, I’ve argued that the highest annual fee Bilt Palladium Card is most worthwhile, followed by the mid-range Bilt Obsidian Card, followed by the Bilt Blue Card. In this post, I’d like to take an in-depth look at the Bilt Palladium Card. What are the card’s perks, and is it worth the steep annual fee? In
Link: Apply for a no annual fee Bilt Blue Card, $95 annual fee Bilt Obsidian Card, and $495 Bilt Palladium Card (Rates & Fees)
Bilt Palladium summary & key details
The Bilt Palladium Card is the most premium card in Bilt’s credit card portfolio. Before getting into why I think it’s worth it, here are the basics of its value proposition:
- Bilt Palladium Card annual fee: $495, with a $95 annual fee per authorized user
- Bilt Palladium Card welcome bonus: 50,000 bonus points and Bilt Gold status after spending $4,000 within the first 90 days (on non-housing purchases), plus $300 Bilt Cash upon approval
- Bilt Palladium Card rewards: 2x points on all eligible purchases (Bilt Rewards points are super useful) plus 4% back on spending in the form of Bilt Cash, which can be redeemed for all kinds of things, including points on rent and mortgage payments, points accelerators on spending, and more (up to $100 in Bilt Cash rolls over each year, and the rest expires)
- Bilt Palladium Card housing rewards: There are two options for earning points on housing payments, as you can redeem $3 in Bilt Cash for every 100 points, for up to 1x points on your payment, or you can skip earning Bilt Cash and instead earn 0.5x to 1.25x points on housing depending on how much you spend on the card relative to your housing payment that month (I’ll walk through an example below)
- Bilt Palladium Card perks and benefits: $200 in Bilt Cash annually as an anniversary bonus of sorts, up to $400 in Bilt travel portal hotel credits every calendar year (this comes in the form of a $200 semi-annual credit, valid for a two-night minimum stay)
- Bilt Palladium Card lounge access: Priority Pass membership, with up to two guests allowed (authorized users also receive a membership) A maximum benefit amount and certain restrictions and limitations apply. Please review (the Mastercard Guide to Benefits) for details.

Why I think the Bilt Palladium Card is worth it
I think the Bilt Palladium Card is the product in Bilt’s lineup that’s most worth considering. Why? For one, the card has a welcome bonus of 50,000 bonus points and Bilt Gold status after spending $4,000 within the first 90 days (on non-housing purchases), plus $300 Bilt Cash upon approval.
Other than this, we’ve never seen a Bilt card have a formal welcome bonus before, and that’s absolutely worth taking advantage of, as the other two cards don’t offer any points with the bonus. At a minimum, the card is worth giving a try for a year.
Beyond that, what intrigues me about the card is simple — it offers 2x Bilt Points on everyday spending, which is pretty incredible. Bilt Rewards points are valuable, as they can be transferred to lots of useful programs, like Alaska Atmos Rewards, Japan Airlines Mileage Bank, and many others.
While we’ve seen some transferable points cards offer 2x points, I think being able to earn Bilt Points at that rate is incredible, and probably beats the other options.
The icing on the cake is that you’re earning 4% back in the form of Bilt Cash on all your spending, and as I see it, there are two redemption options that are most enticing:
- $3 in Bilt Cash is worth 100 Bilt Points on your total rent or mortgage payments, at the rate of 1x points; put another way, you’d get $4,000 worth of housing payments (4,000 points) with $3,000 in spending
- $200 in Bilt Cash (which you’d unlock after $5,000 in spending) can be redeemed for one extra point per dollar on $5,000 worth of non-housing spending, meaning you’d earn 3x points per dollar spent on everyday spending; you can unlock this perk up to five times per year, for up to $25,000 worth of spending
The numbers here are pretty lucrative. Just to give an example with straightforward math, let’s say you spend $100,000 per year on the card:
- You’d earn 200,000 Bilt Points, at the rate of 2x points per dollar spent
- You’d earn at least $4,000 in Bilt Cash, at the rate of 4% back (and that doesn’t factor in the annual Bilt Cash bonus)
- You could redeem $1,000 in Bilt Cash to earn 25,000 bonus points on spending (where you’d earn 3x points) thanks to the points accelerator option, and the other $3,000 in Bilt Cash could unlock earning 1x points on $100,000 in housing payments annually
- You’d also earn Bilt Platinum status, which gives you extra benefits, like some partner status perks, access to better Rent Day offers, etc.
It’s hard to argue with that return on spending, as that’s pretty spectacular.
Bilt Palladium Card earning example: the math on a mortgage
Bilt’s reward system gets complicated pretty fast, so let’s look at a concrete example with a specific mortgage payment.
Using a $3,500 mortgage as an example, below is how your rewards would stack up across the two earning options — Bilt Cash and tiered points earning up to 1.25x points based on your non-mortgage spend.
Monthly card spend (outside of mortgage) | Bilt Cash option | Tiered earning option |
$1,750 (50% of mortgage) | 2,333 points ($70 Bilt Cash) | 2,625 points (0.75x) |
$2,625 (75% of mortgage) | 3,500 points ($105 Bilt Cash) | 3,500 points (1x) |
$3,500 (100% of mortgage) | 3,500 points + $35 leftover Bilt Cash | 4,375 points (1.25x) |
You need to spend $2,625 (75% of $3,500) on non-mortgage purchases to earn 1x points whether you choose the Bilt Cash or tiered earning option. At $3,500 in monthly non-mortgage spending, the tiered option earns more housing points (875 more points per month).
But over a year, that $35 per month in leftover Bilt Cash adds up to $420. That’s enough for two points accelerators (each costs $200 in Bilt Cash, and earns 1x extra point per dollar on up to $5,000 of spending), for a total of 10,000 bonus points. That’s close to the 10,500 extra points the tiered option earns over a year (875 points per month, multiplied by 12 months), so it more or less evens things out.
If you spend more than $3,500 per month on everyday purchases, Bilt Cash is the better choice, because the tiered option caps at 1.25x points, while the extra Bilt Cash can keep funding accelerators, up to five a year for 25,000 bonus points. You’d need about $4,700 a month in everyday spending to max out all five on top of covering your mortgage.
Why the lower annual fee Bilt cards aren’t as good
Above I made the case for the Bilt Palladium Card, but what actually makes the card more compelling than the lower annual fee versions?
Well, I think there’s an argument to be made for getting the $95 annual fee Bilt Obsidian Card, though there are a couple of main considerations:
- The Bilt Palladium Card has a bonus of 50,000 points upon completing minimum spending, so that’s a lot to forgo by applying for the Bilt Obsidian Card
- The two cards have very different rewards structures, as the Bilt Palladium Card offers 2x points on all eligible spending, while the Bilt Obsidian Card offers 3x points on your choice of dining or groceries (dining is uncapped, groceries is capped at $25,000 of spending per year), 2x points on travel, and 1x points on all other purchases
I’d say it’s hard to turn down the welcome offer on the Bilt Palladium Card, but beyond that, the decision comes down to how much you spend in categories that would earn bonus points on the Bilt Obsidian Card.
Bilt card comparison | Bilt Palladium Card | Bilt Obsidian Card |
|---|---|---|
Annual fee | $495 | $95 |
Authorized user fee | $95 per user | $50 per user |
Welcome bonus | 50,000 points + Bilt Gold status after $4,000 in non-housing spending within 90 days, plus $300 Bilt Cash upon approval | $200 Bilt Cash upon approval |
Everyday earning | 2x points on all eligible purchases | 3x on dining or groceries (your choice), 2x on travel, 1x on everything else |
Category caps | Not applicable | Groceries capped at $25,000 per year; dining uncapped |
Bilt Cash | 4% back in Bilt Cash, plus $200 in Bilt Cash annually | 4% back in Bilt Cash |
Hotel credits | Up to $400 per year in Bilt travel portal credits ($200 semi-annual, two-night minimum) | Up to $100 per year in Bilt travel portal credits ($50 semi-annual, two-night minimum) |
Lounge access | Priority Pass with up to two guests | None |
Best for | Big spenders, people who pay rent or a mortgage through Bilt, and anyone who wants the welcome bonus | People with heavy dining or grocery spending |
However, what’s the case for instead applying for the no annual fee Bilt Blue Card? The card is pretty basic — it gives you access to the Bilt ecosystem, but it only earns 1x points per dollar spent. So the simple argument in favor of the card is if you absolutely don’t want to pay an annual fee, but can still get outsized value by redeeming Bilt Cash to earn points on housing payments.
Bilt card comparison | Bilt Palladium Card | Bilt Blue Card |
|---|---|---|
Annual fee | $495 | $0 |
Authorized user fee | $95 per user | $0 |
Welcome bonus | 50,000 points + Bilt Gold status after $4,000 in non-housing spending within 90 days, plus $300 Bilt Cash upon approval | $200 Bilt Cash upon approval |
Everyday earning | 2x points on all eligible purchases | 1x points on all purchases |
Bilt Cash | 4% back in Bilt Cash, plus $200 in Bilt Cash annually | 4% back in Bilt Cash |
Points accelerator | Redeem $200 in Bilt Cash for +1x points on $5,000 of spending, up to five times per year | Not available |
Hotel credits | Up to $400 per year in Bilt travel portal credits ($200 semi-annual, two-night minimum) | None |
Lounge access | Priority Pass with up to two guests | None |
Access to the Bilt ecosystem | Yes | Yes |
Best for | Big spenders, people who pay rent or a mortgage through Bilt, and anyone who wants the welcome bonus | People who refuse to pay an annual fee but still want to use Bilt Cash on housing |
The review describes the Bilt Blue Card as pretty basic, and it only covers it briefly. The “not covered” cells are gaps in the articl
But if you’re a relatively big spender, I think the math on the Bilt Palladium Card really works out quite nicely.
My hesitations with the value of the Bilt Palladium Card
While there’s a lot to like about the Bilt Palladium Card, I think there are some important points to make, about things that concern me, or that I maybe don’t love about the program.
For one, I’m frustrated by Bilt specifically excluding certain spending categories from being eligible to earn points. For example, Bilt states that it doesn’t award points for tax payments put on credit cards. Virtually no other card from a major issuer has such a policy.
That’s a major “spending” category for me, and a way I earn lots of points with other cards. That’s of course Bilt’s prerogative, but it has major implications for how I value the card, and how much spending I can put on it. So that’s not a category where I can earn rewards with Bilt, and it means I need to keep around another great card for everyday spending.
Second, I have a generally hard time recouping the annual fee through the card perks, aside from the incredibly lucrative return on spending. While the card offers a Priority Pass membership, I already receive that through several other premium cards. Furthermore, the up to $400 in hotel credits is valuable on the surface, but I also get so many hotel credits with other premium cards, and the specific way you have to book with these credits limits the usefulness.
Third, there’s just the general question of how sustainable all of this is, and if it will all stick around. The economics here are better for Bilt than they were under the old system, but still, I feel like we’re going to see some more cuts. For example, will Bilt Points continue to be as valuable as they are now, as I can’t imagine the current redemption rates are sustainable for Bilt? Admittedly we know the Bilt to Hyatt transfer ratio will be devalued come 2027, but that’s actually not Bilt’s fault, since it seems Hyatt is driving that change.
I think one of Bilt’s big challenges is that it tends to have a pretty savvy customer base. After all, these are people who care enough to pick up a card specifically to earn housing rewards. Those people are also more likely to take advantage of benefits, maximize their points redemptions, etc.
It’s a much less profitable customer base than with something like Amex, where you have people who don’t really care about the points, but they just want the “status” of spending on an Amex card.
How the Bilt Palladium Card fits into a credit card strategy
The Bilt Palladium Card works best as a catch-all for non-bonus spending, not a replacement for every card. That’s also what makes the tax exclusion particularly frustrating, since tax payments are exactly the kind of category where a great card for everyday spending is valuable.
You need to put significant spending on the card beyond your mortgage or rent to earn the full housing multiplier. But ideally you’re not redirecting spend that would earn more points on another card. That’s why there are other cards I also use for my spending, in order to take advantage of bonus categories. This includes things like using the American Express® Gold Card (learn more) for dining and supermarkets, the Chase Sapphire Reserve® Card (learn more) for airfare and hotel spending, the Atmos™ Rewards Summit Visa Infinite® Credit Card (learn more) for foreign purchases, etc.
A lot of this depends on which earning option you choose, too. If you choose the tiered earning option, moving spending to another card can drop you down a tier. With the $3,500 mortgage example, at $2,625 in monthly everyday spending on the card, you qualify for 1x points on housing. But if you move $300 of monthly dining spend to another card, you drop to 0.75x points, or 875 fewer housing points that month.
As a rule of thumb, if your mortgage or rent is large, it pays to route enough of your everyday spending through the card so you can earn the full housing multiplier. If your housing payment is small or you don’t pay it through Bilt, use the Bilt Palladium Card for whatever doesn’t earn a bonus on another card, and keep your other rewards cards with bonus categories for the rest.

My experience “applying” for the Bilt Palladium Card
In early 2026 we saw Bilt transition from Wells Fargo to Cardless, and existing cardmembers had the opportunity for a seamless transition, so that’s how I acquired this card.
If you were an existing cardmember, there was no hard pull when you applied for the new card, and instead, there was just a soft pull. So unless something absolutely drastic changed since your previous application, you were supposed to also be approved for the new card (however, there are a concerning number of reports of non-approvals).
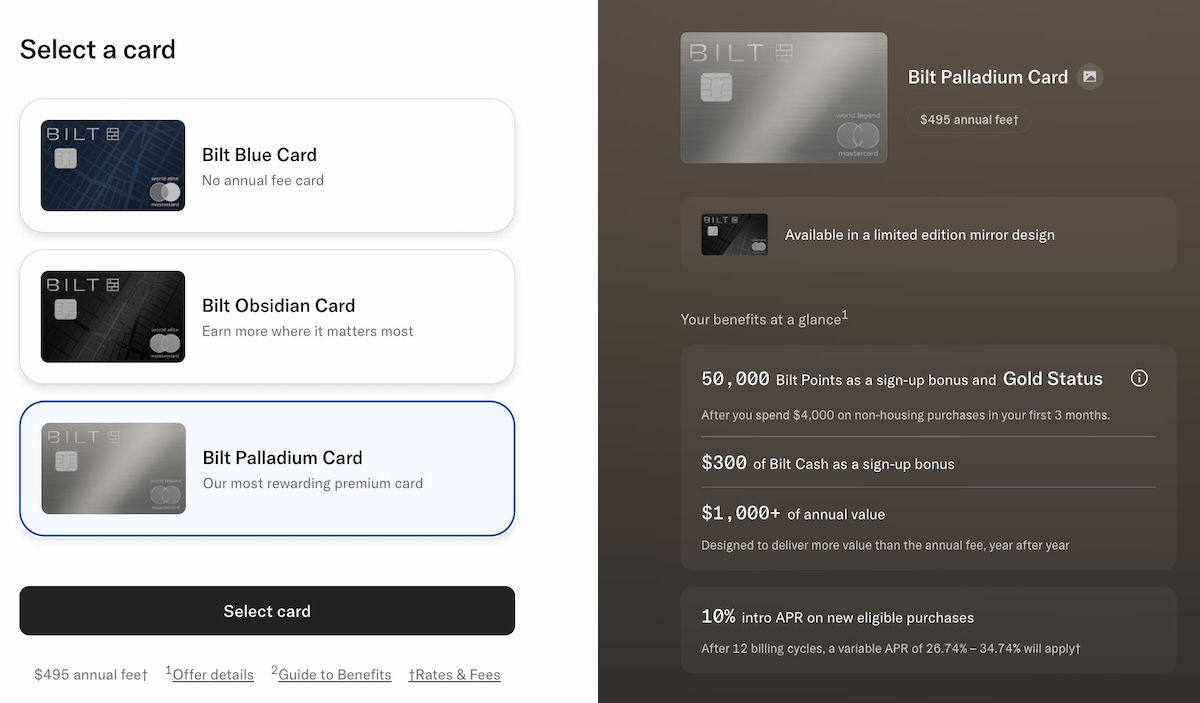
With that in mind, let me share my experience. After going to Bilt’s new credit card page, I logged into my account and clicked the “Apply now” button, and I could choose which card I wanted. I selected the Bilt Palladium Card.
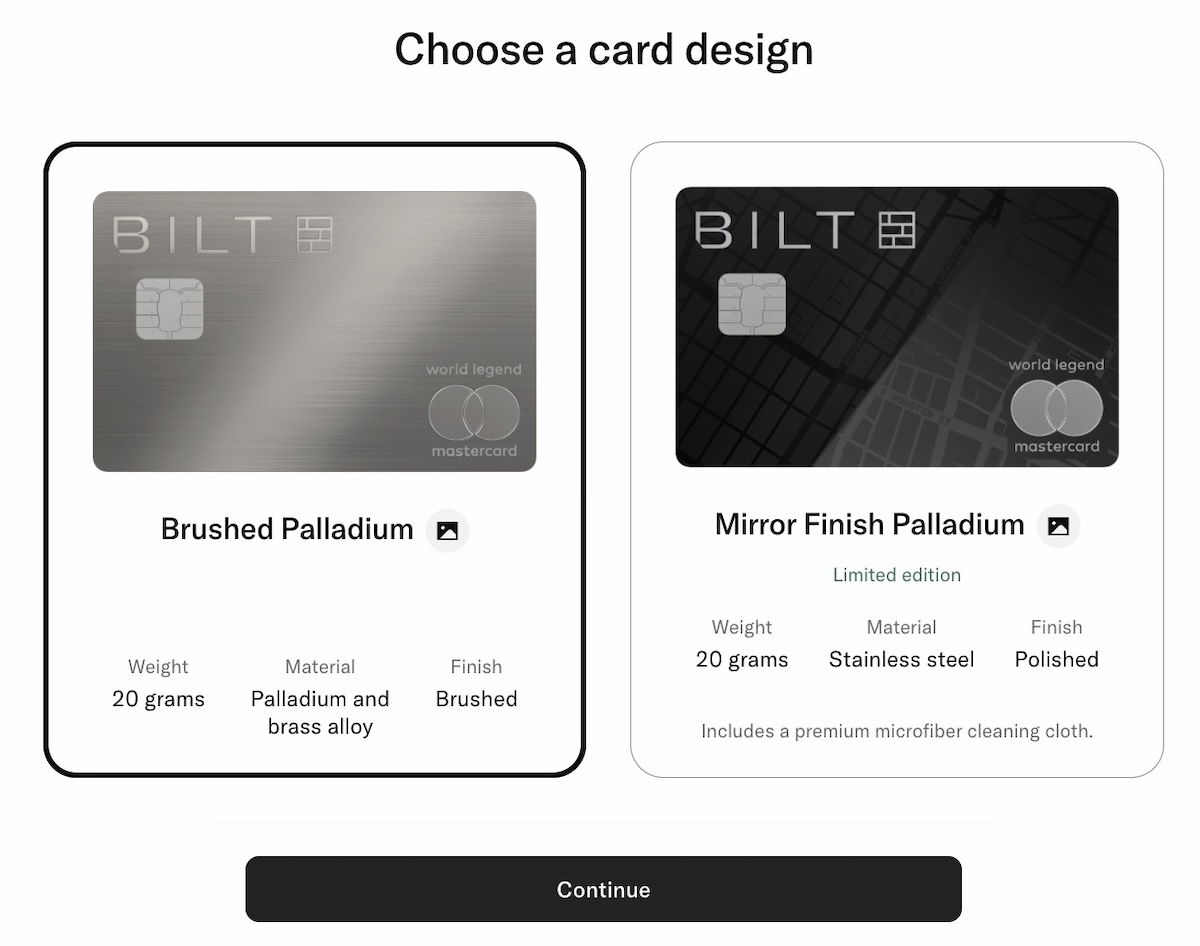
I could then choose my card design, between brushed palladium or mirror finish palladium.
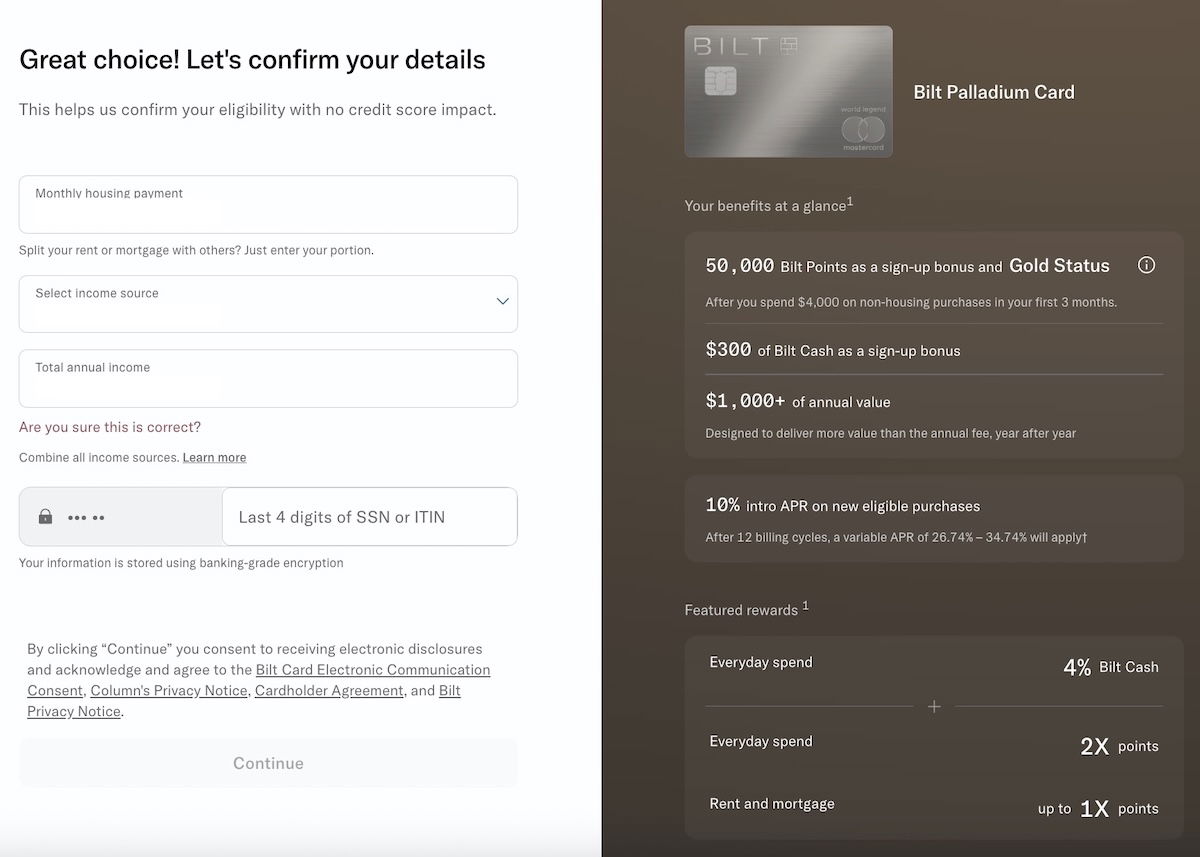
I was then asked to confirm the information I had provided to Wells Fargo in the past, including my monthly housing payment, income, etc.
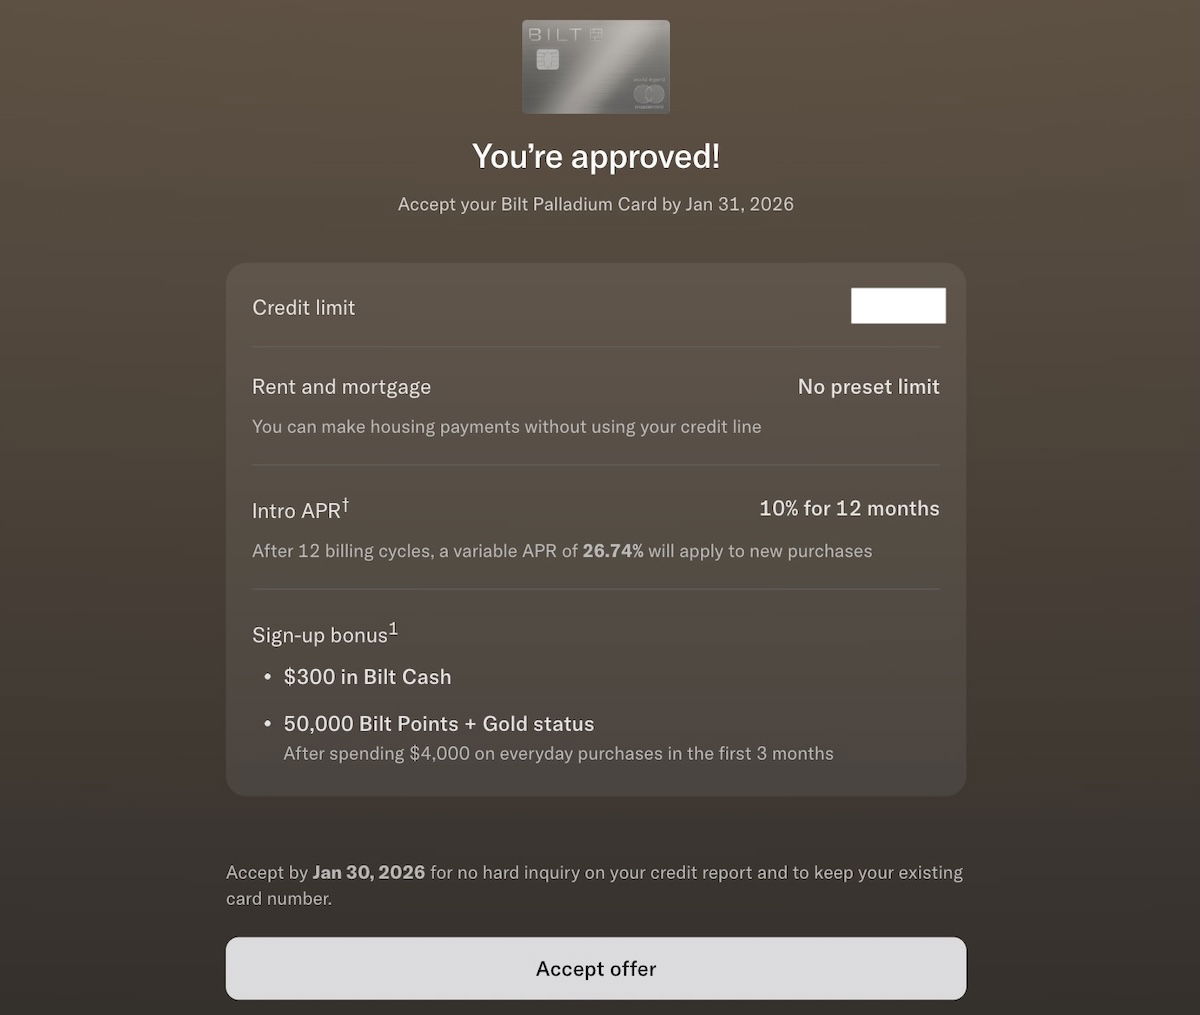
I then submitted that information and found that I was approved, with a big credit line (though it was still about 30% smaller than my Wells Fargo credit line, which was oddly large). Keep in mind that with the transition to Cardless, your rent or mortgage payment no longer counts toward your credit line (since it’s paid by ACH rather than being charged to your card), so that gives a little more flexibility. I was asked if I wanted to accept the offer.
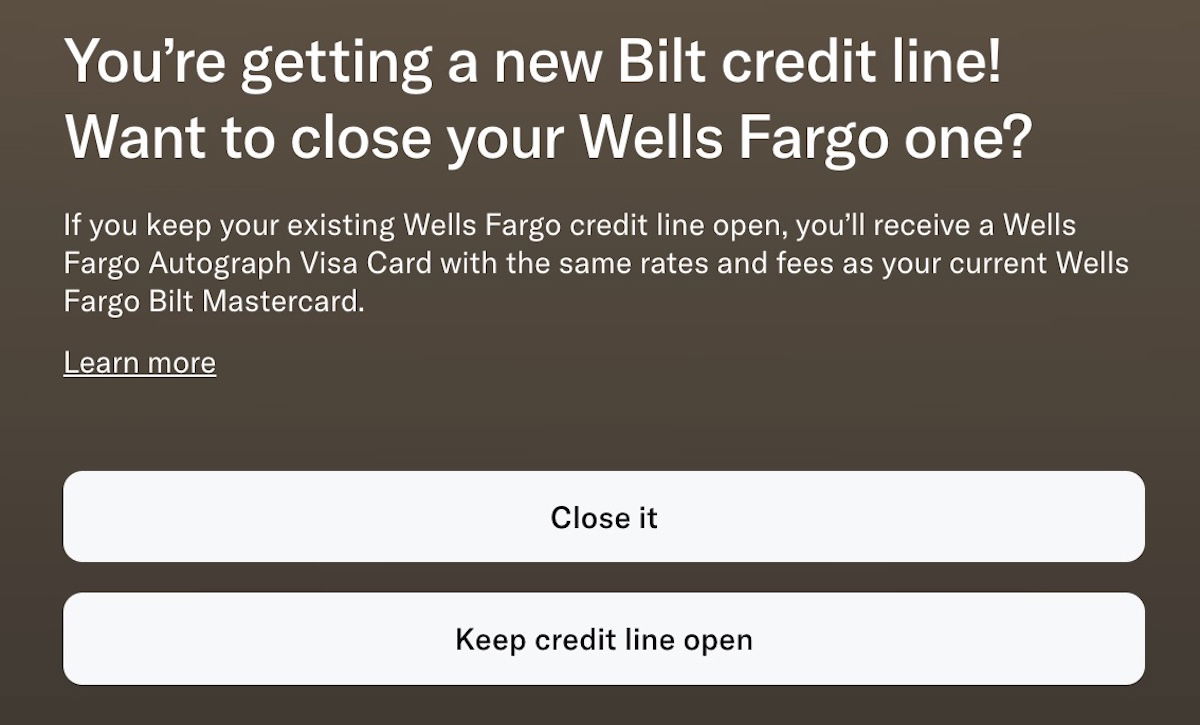
After accepting the offer, I was asked if I wanted to keep my Wells Fargo credit line open, which I didn’t want, so I clicked “Close it.” In theory there’s value to keeping cards open in order to maximize your available credit, which can be good for your credit score. However, I have so many credit cards and so much available credit that I’m no longer trying to keep them open unnecessarily.
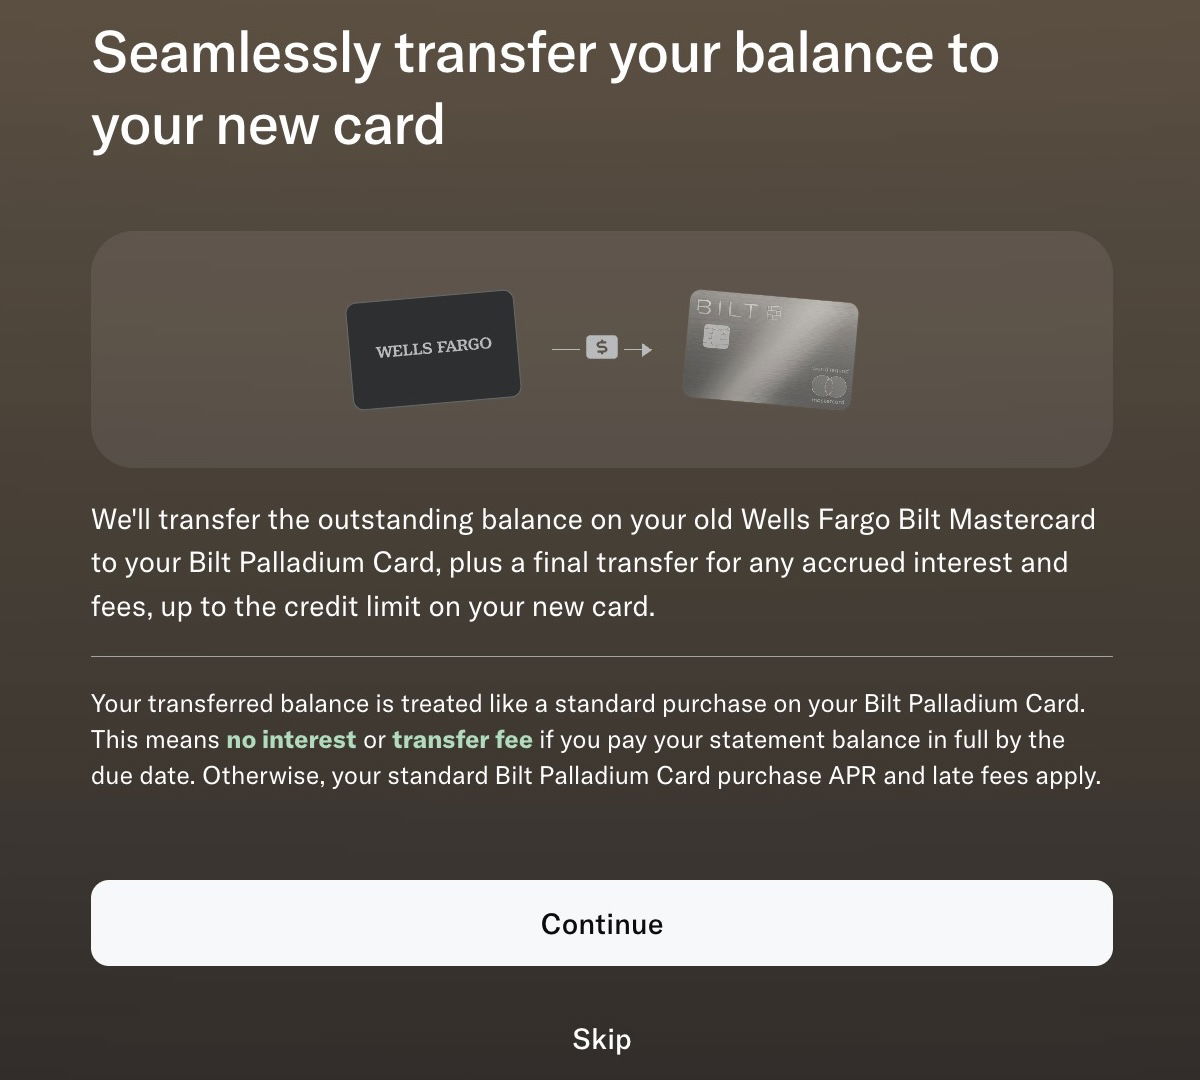
Lastly, I was asked if I wanted to transfer my balance to my new card, and I said that I did.
All-in-all, I found it to be a straightforward process. For what it’s worth, I found that the bonus points and Gold status posted to my account almost immediately after completing the minimum spending (compared to being at the end of a statement period, or something).
Bilt Palladium Card FAQs
Bottom line
Bilt has three credit cards at different price points, and I’d argue that the $495 annual fee Bilt Palladium Card is the obvious choice, assuming you spend a decent amount on your credit card, and on rent or mortgages.
It’s the only card with a substantial welcome bonus, and as I view it, that bonus more than covers the card’s annual fee for the first year. The biggest selling point of the card is that it earns 2x points on all spending, which I’d argue makes it one of the best cards out there for everyday spending, given the value of Bilt Points.
Then your spending earns you Bilt Cash, which you can redeem for a combination of housing payments and to earn even more bonus points, so that you can earn 3x points on up to $25,000 of spending annually. Alternatively, you can skip Bilt Cash and earn up to 1.25x points on housing payments, depending on how much you spend on the card.
However, I also have concerns. I don’t like how tax payments aren’t eligible for earning points, and I’m not sure how easily I’ll be able to recoup the annual fee, given the lack of meaningful benefits outside of Bilt Cash and the Bilt hotel credit.
For now I’m viewing this as a card that I’m giving a try for a year, and then I’ll decide on my long term strategy based on how things play out. So far my experience has been positive for the most part, and I’ve earned a ton of points, including thanks to the points accelerator feature. We’ll see how this all evolves over time, though.
How are you thinking about which Bilt card makes the most sense, and which did you decide on, if any?


I have different concerns. AUs don’t count for the “accelerator” of spending $200 Bilt cash for an extra point on future spending. This makes we wonder why on earth I’m paying $95 for my husband other than to keep family peace. Also, the elephant in the room is Cardless and their… struggles… to achieve anything close to the customer service one expects from traditional card issuers. Also, as a newer issuer, bin fraud is rampant and a major pita when it happens.
Every Bilt article from anyone seems to be a test of reading comprehension.
Someone needs to make or have AI make a widget that says if I have x $ regular spending monthly and y $ of housing spending I end up with Z $ of each BILT currencies.
Way too confusing between points and cash. no thanks
It's interesting that some people find the Bilt Card very rewarding and Bilt Cash very easy to use . . . in spite of others telling them how bad the Bilt Card is. DoC presented a very straightforward approach to use the card and Bilt Cash.
Lee, there are systemic issues with 2.0, and undeniably it is worse for renters than 1.0 (because there’s now a fee for rent that you have to spend to offset). However, yes, some extremely savvy, often wealthy users *might* receive outsized value if they “game” this product. But there are drawbacks, like the relatively unusable BILT Cash glut some of us are referring to here. By all means, insert your meta-commentary and plausible deniability, but...
Lee, there are systemic issues with 2.0, and undeniably it is worse for renters than 1.0 (because there’s now a fee for rent that you have to spend to offset). However, yes, some extremely savvy, often wealthy users *might* receive outsized value if they “game” this product. But there are drawbacks, like the relatively unusable BILT Cash glut some of us are referring to here. By all means, insert your meta-commentary and plausible deniability, but I see your comment for what it really is: Fluff.
Lee, if you actually followed DoC, you’d know, many regulars there have been highly critical of BILT 2.0… are you just fluffing for Ankur? Clearly, BILT has an active online mafia that likes to come on and say good things about their products or insert plausible deniability, and try to discredit any naysayers, like you just tried to do.
DoC's approach excluded consideration of rent/mortgage payments. It's okay that many people have a problem with Bilt and it's okay if they're mad. But, there are those who do quite well with Bilt. The problem is that those for whom it doesn't work try to convince those for whom it does work. And, in your case, you constantly denigrate those for whom it does work. I'm sorry Bilt didn't work out for you and I...
DoC's approach excluded consideration of rent/mortgage payments. It's okay that many people have a problem with Bilt and it's okay if they're mad. But, there are those who do quite well with Bilt. The problem is that those for whom it doesn't work try to convince those for whom it does work. And, in your case, you constantly denigrate those for whom it does work. I'm sorry Bilt didn't work out for you and I don't want to deny your right to be mad. But, don't slam those who say they do well by the card.
Lee, there’s a big difference between a product working for a tiny group of people who know how to rig the system, and a product being a 'good deal' for the average renter. If you have to jump through so many hoops and ignore the actual rent features just to make the 2.0 cards competitive with a standard 2% cash-back card, it’s a bad value proposition for the vast majority of consumers. Pointing this out...
Lee, there’s a big difference between a product working for a tiny group of people who know how to rig the system, and a product being a 'good deal' for the average renter. If you have to jump through so many hoops and ignore the actual rent features just to make the 2.0 cards competitive with a standard 2% cash-back card, it’s a bad value proposition for the vast majority of consumers. Pointing this out isn't 'madness,' it's basic consumer advocacy. Do keep shilling for them, though.
You have actual statistics that illustrate only a small number of people benefit from the card? Right. You seem to have a lot of anger going on. Your employer's health insurance likely has a counseling benefit. You might want to look into it. Get well soon.
Lee, faking mental health advice because you’re losing a debate about a credit card says more about you than me. No one needs statistics to realize that when BILT introduced new rent fees and coupon credits, the math got worse for most consumers. When the annual fees hit for Palladium, a lot of folks are gonna downgrade or close the card. Face the music.
Your claims of a multitude who are worse off without backing sounds a lot like Trump's claims of attendance at his speeches without backing.
Ah, since amateur psychology didn't work, you've now pivoted to political commentary.
'Thank you for your attention to this matter.'
1990 is the new Tim Dunn
If by Tim Dunn, you mean 'persistent,' yes. 100%. If by Tim Dunn, you mean, sycophant for a specific brand, like Delta or BILT. Nope. I'm for consumers (and workers). There's a huge difference advocating for them, rather than simply shilling or cucking or sane-washing corporate greed. Try to learn the difference, friends.
Consumer advocacy is a far more noble cause than shilling for a corporation.
Many of us are going to have a glut of expiring BILT Cash. It’s probably by-design, and we’re falling into that trap.
I put all my non category spend on this card. 3x earn on that spend and the best transfer partners out of all cc’s right now makes this a keeper. 200 portal credit combined with 100 credit you can get from converting bilt cash makes this similar to the FHR credit on the plat. I hope they change their stance on points for tax payments.
3x but up to 25,000 points and after using 5x $200 BC for that Accelerator, but after that, back to 2x. See, it’s far more complicated and nuanced, which is why many preferred 1.0, but those days are over because Wells Fargo was tired of losing $10 million/month on being Ankur’s sugar-daddy. Yep. Nope.
As a resident of an Alaska hub this is an awesome card for me. Until someone else transfers to them I will hold it. Easy to offset the fee with weekend stays in hotels that otherwise don't accept points too. My 2k mortgage I now get points for that I didn't before so that's $200+ in value a year that I didn't get previously. Easily worth $495.
Something I haven't seen mentioned is Walgreens...
As a resident of an Alaska hub this is an awesome card for me. Until someone else transfers to them I will hold it. Easy to offset the fee with weekend stays in hotels that otherwise don't accept points too. My 2k mortgage I now get points for that I didn't before so that's $200+ in value a year that I didn't get previously. Easily worth $495.
Something I haven't seen mentioned is Walgreens expires 30 days from use so claim it at the end of the month and again at the beginning of the month for $20 to spend.
I think we've already seen a bit of a devaluation with the 100k cap on Rent Day bonuses (kicking myself for missing out on the Avios transfer, could have used that now). The limited usage of Bilt Cash (after accelerators are exhausted and paying for the additional points from my mortgage) is also very much annoying. But the combo of Bilt Cash + hotel credit has covered the annual fee, and the card has been...
I think we've already seen a bit of a devaluation with the 100k cap on Rent Day bonuses (kicking myself for missing out on the Avios transfer, could have used that now). The limited usage of Bilt Cash (after accelerators are exhausted and paying for the additional points from my mortgage) is also very much annoying. But the combo of Bilt Cash + hotel credit has covered the annual fee, and the card has been a points earning machine for me.
I'm a few K $ away from Bilt Platinum, which will result in additional savings when I can do the Flying Blue Gold status match, now that Air France started charging for J long-haul seat selection to the US (Boo to you Air France for copying BA).
People need to stop asking about or expecting ability to downgrade palladium. BILT has repeatedly said it’s not happening. And if I were them I wouldn’t let cardholders downgrade at all either.
But I would let them apply for a new card….with no bonus of course (should the other 2 cards eventually offer a bonus, and they should!)
Gotta stop Gamers from wrecking the program.
Hope you're on BILT's payroll, because otherwise, you're doing their dirty work for free.
I would like to pay my mortgage thru BILT and get obsidian. But they’re not a serious business and program is already ripe for devaluation. I’m also not a fan of BILT cash. So many coupons with too many restrictions.
I’ve found bilt cash to be extremely valuable beyond just rent. The $200 portal credit +$100 bilt cash has already been worth near face value. I booked at a hotel that was also eligible with Hyatt. With recent Chase devaluations, even if they do devalue next year I don’t find too many more worthwhile options. Accor is an underrated transfer partner for those who travel to Europe or Asia often. All in all I’m extremely...
I’ve found bilt cash to be extremely valuable beyond just rent. The $200 portal credit +$100 bilt cash has already been worth near face value. I booked at a hotel that was also eligible with Hyatt. With recent Chase devaluations, even if they do devalue next year I don’t find too many more worthwhile options. Accor is an underrated transfer partner for those who travel to Europe or Asia often. All in all I’m extremely happy with it and would be ok with a small devaluation to keep the programs viable.
LOL. You one of those “Close Friends” that gets points for every positive BILT mention on socials?
If you’re not running your housing payments thru BILT (and have the spend to unlock the points, of course). BILT isn’t worth it.
Me personally, I would let BILT anywhere near my housing. Maybe in future if and when they clean up their act. At least get to Citibank or US Bank level of bad.
As with any card, it's a fit for some and not a fit for others. And, as with any card, you need to study it to see whether it's a fit for your specific circumstances. Anecdotal comments trying to convince you one way or another -- to get it or not get it -- are meaningless.
"Anecdotal" ... oof, nice double-speak.
Translation: When someone highlights a legitimate flaw or a math problem with Bilt, it’s just "meaningless anecdote." But when someone praises it, it’s suddenly hard "data and facts."
Tim Dunn perfected this tactic (in-favor of Delta). Rewrite the rules of logic so your preferred brand can never actually lose an argument! Huzzah!
It’s just ok for this first year. 50K SUB. 2x everything. But, unless you use BILT Cash to offset the rent fee, you’re gonna end up with way too much excess BILT Cash, and it’ll just expire. I suspect there’ll be a lot of downgrades or card closings upon renewal.
Without rent/mortgage it's a far less enticing card.
That JAL transfer bonus made the fist year makes it unmatchable for me, 2x round trip business during blossum season for ~110k points is absurd.
I'll downgrade or close next year as I see no way that it continues to earn at its current rates.
Drew, you’re lucky to have both taken advantage of the transfer, and actually found availability to redeem with JAL. Since the bonus, availability has been a real problem, so many others who speculatively transferred without immediately confirming tickets are disappointed when they have a bunch of JAL points they can’t use for what they really wanted or expected.
Totally agree. Have around $2k useless Bilt Cash as without Mortgage/HOA how would I use them? $100 a month on a min 2-night hotel stay? Blade? Little $5/$10 credits
Nice for the SUB and 2x earnings (upped to 3x with multiplier) but Bilt cash doesn't serve any purpose
Marc gets it. Bilt artificially inflates the card's perceived value by giving you "Cash" that is heavily restricted by expiration dates and hyper-specific uses (like minimum hotel nights or niche partners, some of which are still "Coming Soon" for 6 months now...) If you can't use the coupon book, that value evaporates. The math don't work...
I’m the target market for this card (high income + spend, VHCOL region, high rent, fairly young, prefer a one-card setup, all in on Atmos/Hyatt) but until they invest in proper customer support, I’m not going to apply. How does your $495 AF card only offer AI chatbot and Twitter DM support? It’s ridiculous.